
How Much Bitcoin Should You Actually Own?
Ask how much bitcoin should I own and you want a number. Ask how much bitcoin should I buy and you want a rule. The honest answer disappoints both: there is no fixed figure that is correct for everyone, because the right amount is a position-sizing decision, not a constant.
Newcomers hunt for a target - one coin, ten coins, "enough to retire." Professionals treat the same question as risk budgeting: how much of this volatile asset can a portfolio absorb before it starts driving every outcome. That gap explains why published expert allocations run from roughly 1% to 70% of a portfolio for the same cryptocurrency.
A useful anchor sits in the middle. The world's largest asset manager frames Bitcoin sizing at 1-2% of a diversified portfolio as a risk-budgeting choice, per the BlackRock Investment Institute. Treat that as a reference point to understand - not as advice, and not as your number.
AI Summary
There is no single correct amount of Bitcoin to own; the right number is a function of your risk capacity, time horizon, and conviction in long-term adoption. This article works through four lenses - portfolio percentage, formal position-sizing models, scarcity math, and loss tolerance - and shows why small allocations dominate serious analysis.
No universal number: the amount is personal, driven by variables, not a fixed constant.
Wide expert spread: documented positions range from ~1% (Ray Dalio) to 1-2% (BlackRock) to ~70% (high-conviction outliers).
Small % ≠ small risk: a modest allocation contributes a disproportionate share of total portfolio risk.
The quant view: models like Kelly and Black-Litterman turn "how much" into math - and usually output fractional sizes.
Scarcity math: a 21M cap against tens of millions of millionaires makes whole-coin ownership structurally rare.
The afford-to-lose method: size from discretionary income, not from money you need to live.
"To be rich" arithmetic: every such figure depends on an unknowable future price - illustrative only.
Pacing matters: lump-sum versus dollar-cost averaging is a separate, survivability-driven choice.
How Much Bitcoin Should You Own? (The Short Answer)
There is no fixed amount that is right for everyone. The correct size depends on measurable personal inputs - how much you can lose, your time horizon, and your conviction. As an institutional reference, a diversified portfolio commonly caps Bitcoin near 1-2%, but individual circumstances shift that materially in either direction.
The question is best answered with a method, not a figure. Below are the four lenses this article uses. Each answers a different underlying question, and most thoughtful investors combine them rather than picking one.
Four Ways to Size a Bitcoin Position
Approach | Core Question It Answers | Best For |
Portfolio % | What share of my net worth should this be? | Anyone building a diversified portfolio |
Position-sizing model | What does the math say given my assumptions? | Quantitatively minded investors |
Scarcity lens | How much can I realistically expect to hold? | Understanding expectations and status framing |
Risk-capacity lens | How much can I lose without changing my life? | Every investor, as the final sanity check |
Why There's No Single "Right" Amount
The right amount of Bitcoin is a function of your personal variables, not a universal constant. Two people with the same net worth can correctly hold very different amounts because their income stability, time horizon, and tolerance for a deep drawdown differ. The number falls out of your circumstances - it is not handed to you.
One variable dominates and is routinely ignored: drawdown survivability. Bitcoin has historically been roughly four times as volatile as US stocks, per Morningstar, and several times more volatile than gold. It has also fallen 70-80% or more in past cycles - down 84% from its 2017 peak and 77% from its 2021 peak. The real question is not "how much do I want," but "how much can I hold through that."
What Actually Determines Your Number
Variable | Why It Moves Your Number |
Risk capacity | Money you can genuinely afford to lose sets the ceiling. |
Time horizon | Longer horizons can absorb deeper, longer drawdowns. |
Income stability | Reliable income supports steadier accumulation and holding. |
Existing net worth | The same dollar amount is a very different % of each portfolio. |
Conviction in adoption | Belief in long-term adoption justifies (for some) a larger tilt. |
Drawdown tolerance | The point where you'd panic-sell caps a responsible position. |
Start With What You Can Afford to Lose - The Discretionary-Income Method
A practical floor is to size the position from discretionary income - what remains after essentials, an emergency fund, high-interest debt, and retirement contributions - and not from money earmarked for living costs. This method sets a ceiling before any market view enters the picture, which is why it survives contact with volatility.
The worked example makes it concrete. Suppose monthly income minus core expenses minus savings and retirement leaves $400 of true discretionary money. Bitcoin then draws from a portion of that $400, not all of it - the rest stays flexible for life. This keeps a volatile asset funded by money whose loss would sting but not destabilise you.
Pair it with a simple self-check: if a 50% drop would make you panic-sell, the position is too large. It is a mirror, not a rule imposed on you.
The Portfolio Allocation Approach - 1%, 5%, or 10%?
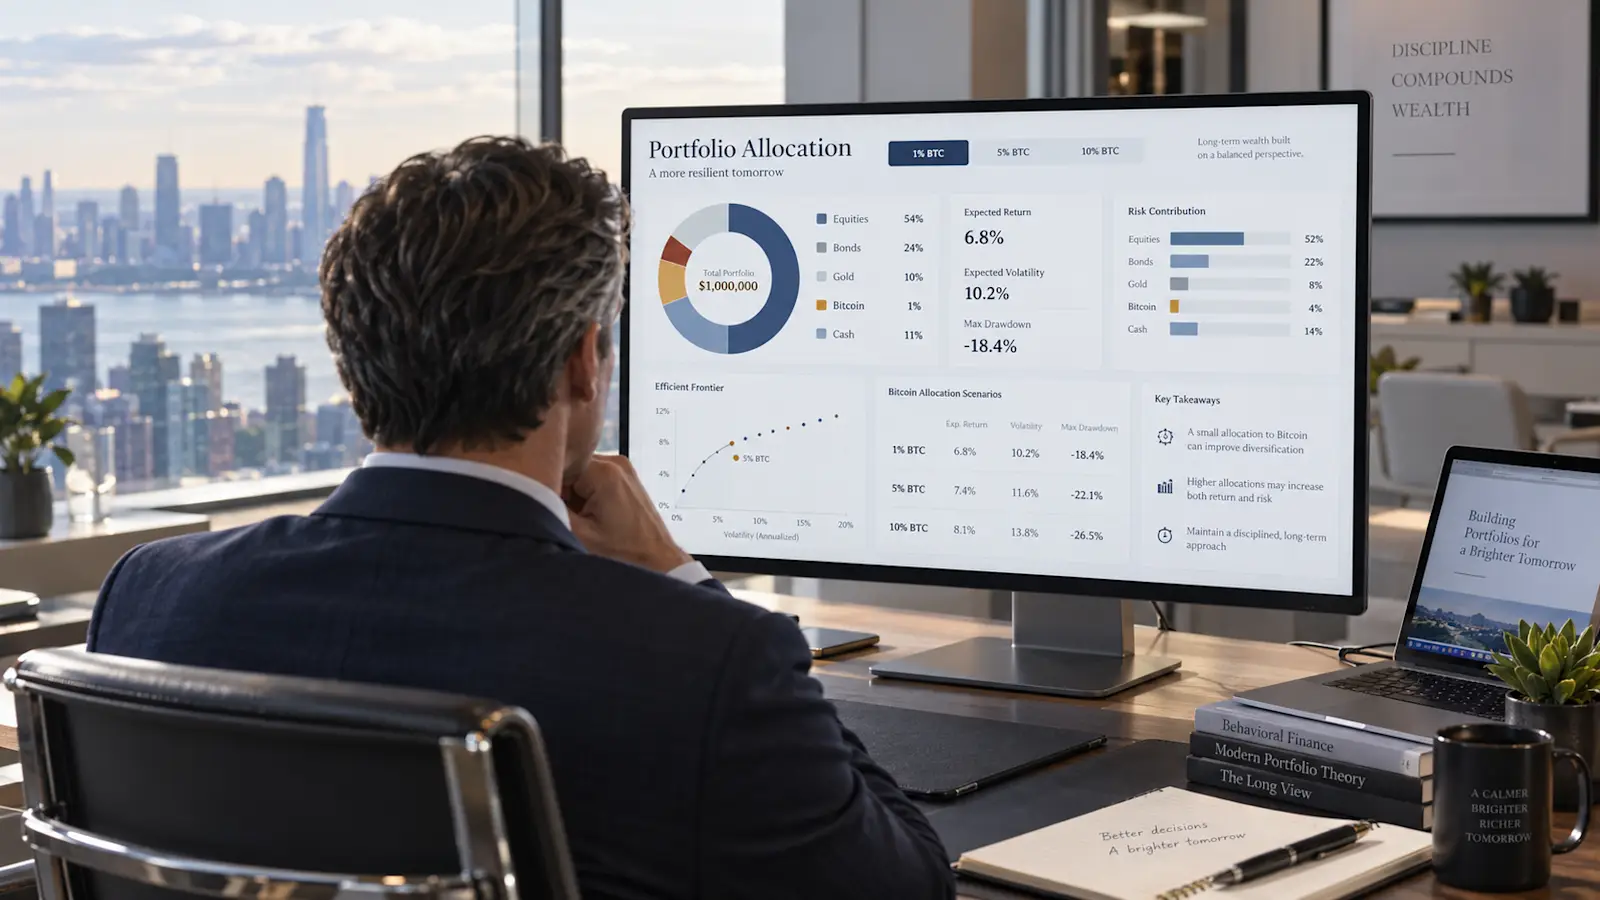
The most common professional method sizes Bitcoin as a percentage of your total portfolio and treats that percentage as a risk-budgeting decision rather than a bet on price. The core question shifts from how much should I invest in bitcoin in dollars to how much total portfolio risk am I willing to hand to one volatile asset. That reframing is what keeps most disciplined allocations small.
The reason is that risk contribution scales non-linearly. A tiny weight can consume a large share of a portfolio's total volatility because Bitcoin is so much more volatile than stocks and bonds, and because its correlation to those assets is unstable. BlackRock's own risk-budgeting work illustrates the low end; Morningstar quantifies what happens as you climb.
Allocation vs Portfolio Risk Contribution
Portfolio Allocation | Approx. Share of Portfolio Risk / Volatility Impact | Typical Profile |
1% | ~2% of total portfolio risk | Cautious first exposure |
2% | Around the practical institutional cap | Diversified, risk-aware |
5% | Over 20% of total risk; ~16% more volatility than a 60/40 | Higher conviction, higher tolerance |
10% | Roughly +41% volatility versus a 60/40 | Aggressive |
25% | ~83% of total risk; more than double the volatility | Extreme / concentrated |
Sources: risk-budgeting framing and the 1%/4% figures from BlackRock; the 5%/10%/25% figures from Morningstar. A 4% allocation, per BlackRock, contributes roughly 14% of total portfolio risk.
There is no consensus on the "right" weight, and the spread among credible names is the clearest proof. The same asset draws allocations from about 1% to 70% depending on who is holding it and why.
What the Experts Actually Hold / Recommend
Source | Stated Bitcoin Allocation | Rationale / Caveat |
Ray Dalio | ~1% (his stated view) | Small position as an uncorrelated store-of-value hedge |
BlackRock | 1-2% reference range | Risk-budgeted; above 2% skews portfolio risk |
Morgan Stanley | Up to 4% | Only for "opportunistic growth" profiles; 0% for income/preservation |
Fidelity | ~2% (low single digits) | Access via regulated products; sized as a small diversifier |
ARK / Cathie Wood | Escalated 0.5% → 6.2% → 19.4% | Model output maximising past risk-adjusted returns; assumption-heavy |
Ricardo Salinas | ~70% | Extreme, high-conviction outlier; not a template |
These are documented positions, not recommendations. The takeaway is the spread itself: identical asset, allocations spanning roughly 1% to 70%, which is why no honest source can hand you one universal number.
The Mathematical Answer - Position-Sizing Models
Quantitative finance treats "how much" as a position-sizing problem solved with formal models rather than intuition. Two frameworks dominate the conversation: the Kelly Criterion and the Black-Litterman model. Both take your assumptions as inputs and return a weight - and both, applied honestly to Bitcoin, tend to collapse toward small, fractional positions when conviction is uncertain.
The practical difference matters. Kelly maximises long-run compounded growth from the odds of winning and losing. Black-Litterman blends your view of Bitcoin's return advantage with the market's equilibrium and a confidence weight. Different machinery, similar conclusion: neither justifies betting the portfolio.
Two Position-Sizing Models
Model | What It Inputs | What It Outputs |
Kelly Criterion | Your edge and the win/loss odds | The growth-maximising fraction of capital |
Black-Litterman | Expected outperformance + your confidence level | An implied portfolio weight |
Shared input reality | Probabilities for Bitcoin are genuinely unknown | Small errors swing the output sharply |
Shared limitation | Neither knows the future | A thinking tool, not a verdict |
The Kelly Criterion
Kelly sizes a position to maximise long-run compounded growth based on your edge and the odds. In practice, investors rarely use "full Kelly" for a volatile asset - most apply fractional Kelly (half or quarter) to survive the swings, because full Kelly on something as jumpy as Bitcoin invites brutal drawdowns. The formula is only as reliable as its probability estimate, and for Bitcoin that estimate is genuinely unknown. Treat Kelly as a discipline for not oversizing, not as a precise dial.
The Black-Litterman Model (the "Quant" Answer)
Black-Litterman derives an allocation from an assumed return advantage over equities plus a confidence level. You pick how much you expect Bitcoin to outperform, set your conviction, and the model returns a weight. The catch that popular coverage buries: the output is extremely sensitive to those two assumptions. Nudge the expected outperformance or your confidence and the "answer" moves substantially. That makes it a structured way to think, not a number to obey.
The Scarcity Math - How Much Bitcoin Can You Actually Own?
With a fixed cap of 21 million coins and a global population in the billions, the arithmetic of scarcity means whole-coin ownership is structurally rare. This reframes the question from how much bitcoin do you need to how much is even available per person - and the honest answer is: far less than most people assume.
Run the numbers. Roughly 20 million BTC have already been mined - about 95% of the cap - with fewer than one million left to issue slowly until around 2140, per CoinDesk. On top of that, research from firms like Chainalysis estimates several million coins are permanently lost, shrinking the effective float further. Against roughly 58 million US-dollar millionaires worldwide (UBS Global Wealth Report 2026), there is only about 0.3 BTC each if every millionaire bought an equal share. Scarcity, though, does not guarantee price appreciation - it only constrains supply.
Bitcoin Scarcity in Numbers (verify live figures before publishing)
Metric | Figure / Note |
Maximum supply | 21,000,000 BTC (hard-coded) |
Mined to date | ~20 million BTC (~95% of the cap) |
Estimated permanently lost | ~3-4 million BTC (estimates vary by methodology) |
Effective float | Roughly 16-17.5 million spendable BTC |
BTC per millionaire (illustrative) | ~0.3 BTC if ~58M millionaires split the supply equally |
The "1 BTC Club" and Holder Tiers - Where Would You Rank?
Because supply is capped, small absolute amounts already place a holder high in the global distribution. You do not need a large stack to sit in a rare tier - the scarcity does the work. This is also where the how much bitcoin should I own to be rich question quietly turns into a status question rather than a wealth guarantee.
The distribution data is striking. Owning a single coin has historically placed a holder in roughly the top 2-3% of on-chain holders, since only about 2.3% of addresses hold at least 1 BTC (Grayscale Research). A widely cited thought experiment by analyst Jake Levison put 0.28 BTC as the top 1% of eventual global adoption - a figure he popularised around 2018-2020, assuming a 21M cap and about a billion future users, not a forecast. Meanwhile, around 74% of addresses hold under 0.01 BTC, so most participation is fractional. Grayscale also notes that roughly 15-16% of supply has not moved in over a decade, so the genuinely liquid float is smaller than the mined total.
Holder Tiers (Illustrative) (distribution snapshot - verify live figures; not a target or forecast)
Holding | Approx. Global / On-Chain Standing | Note |
<0.01 BTC | The large majority (~74% of addresses) | Fractional ownership is the norm |
~0.28 BTC | "Top 1% of eventual adoption" thought experiment | Levison's assumption-based figure |
1 BTC | Roughly top 2-3% of current on-chain holders | Rare, but reachable gradually |
10+ BTC | Well into the upper tail | Concentrated holding |
Ranking high in the distribution is not the same as a financial goal - size to your circumstances, not to a leaderboard.
Building a position gradually. Because meaningful accumulation is structurally hard and most people buy in fractions over time, some structures are built specifically for gradual, custody-safe accumulation. Binaxity's co-investment model lets a user bring cash (from $50) that is matched 1:1 to purchase Bitcoin held with qualified custodians in a bankruptcy-remote SPV, on an interest-only basis with no price-driven margin calls. It is one illustration of structured accumulation - see how the 1:1 co-investment model works.
How Much Bitcoin Do You Need to Be Rich?
There is no amount that makes anyone rich by default. "Rich" depends on your cost of living, and any Bitcoin figure attached to it depends entirely on a future price that cannot be known. Every "how much bitcoin do you need to be rich" answer is therefore arithmetic built on an assumption, not a plan.
The method that circulates in the space is market-cap parity: pick a target total market capitalisation, divide by the coin supply, and read off an implied price. Named third-party scenarios make it concrete - all illustrative, all attributed. ARK Invest's 2030 base case models a roughly $16 trillion market cap; its bull case runs far higher; and a simple gold-parity thought experiment asks what happens if Bitcoin, framed as "digital gold," approached gold's total market value. Critics counter that Bitcoin has no cash flows and cannot be valued this way at all - a fair objection worth holding alongside the math.
Illustrative Market-Cap Scenarios (not predictions) (attributed; illustrative only - not advice)
Scenario / Source | Implied Total Market Cap | Illustrative Implied Price per BTC |
ARK Invest - 2030 base case | ~$16 trillion | ~$760,000 |
ARK Invest - 2030 bull case | ~$30 trillion+ | ~$1.5 million |
Gold-parity thought experiment | ~$30 trillion (gold's market value) | ~$1.5 million |
These scenarios are not predictions and not investment advice; nobody, including this article, expects any particular outcome. The more useful reframing is to stop asking what amount would make you rich and start asking what amount you can hold without harming your finances.
Buy It All at Once, or Spread It Out? (Lump Sum vs DCA)
Dollar-cost averaging (DCA) spreads a fixed total across regular intervals to reduce timing risk, while lump-sum deploys the whole amount once. Deciding how much bitcoin should I buy is only half the question - the other half is over what period, and the two are genuinely different problems.
The trade-off both camps tend to skip: historically, lump-sum has often outperformed DCA in rising markets because time-in-market beats timing. But DCA materially reduces the behavioural risk of buying a local top right before a 70-80% drawdown. Frame it as a survivability decision, not a returns-optimisation one.
Lump Sum vs DCA
Dimension | Lump Sum | Dollar-Cost Averaging |
What it optimises for | Maximum time-in-market | Smoother average entry price |
Behavioural risk | Higher regret if it drops soon after | Lower; discipline is built in |
Timing risk | Concentrated in one entry point | Spread across many entries |
Who it suits | Strong stomach, long horizon | Anyone wary of buying a top |
Common Mistakes When Deciding How Much Bitcoin to Buy
The most damaging sizing errors are behavioural, not mathematical. If you are weighing how much btc should I own, these are the traps that turn a reasonable position into a painful one.
Sizing to a "get rich" target instead of a loss-tolerance limit.
Using money needed for rent, bills, or the emergency fund.
Ignoring that Bitcoin has repeatedly drawn down 70-80%.
Having no plan for custody and counterparty risk.
Treating a portfolio percentage as fixed instead of rebalancing it back to target.
A Practical Framework - How to Decide Your Own Number
Instead of a figure, run four self-assessment questions and let the output be personal. This is how the title actually gets answered without anyone handing you advice: you assemble the tests, and the ceiling reveals itself. No single competitor puts these in one place, so here they are as one checklist.
Your Personal Sizing Checklist
Ask Yourself | Why It Sets Your Ceiling |
Could I hold through an 80% drop without selling? | Your true holding-through point caps the position. |
Is this money I need in the next 3-5 years? | Money with a near-term job should not be here at all. |
What share of net worth still lets me sleep? | Comfort, not maximisation, defines a durable size. |
Am I sizing to FOMO, or to a plan? | Fear-driven sizing is the one that gets sold at the bottom. |
Answer those honestly and you will not need anyone to tell you how much bitcoin should you own - the number that survives all four is yours.
For readers who would rather build a Bitcoin position gradually than time a single purchase, Binaxity's Investment Line of Credit offers a structured, no-margin-call route worth understanding.
FAQ
How much bitcoin should I buy as a beginner?
There is no set beginner amount; start from what you can afford to lose, not from a target. Institutions often use a 1-2% portfolio reference range as a starting point to understand. Many people begin small - some structured products start from as little as $50.
How much should I invest in bitcoin?
Size it as the share of your total portfolio you could watch fall sharply without disruption. The risk-budgeting logic is that even a small percentage contributes an outsized share of portfolio volatility. Because this is personal, consider a qualified advisor for your situation.
How much bitcoin do you need to be rich?
No amount guarantees wealth, because any figure depends on an unknowable future price. The "to be rich" math you see online is illustrative arithmetic, not a forecast. A more useful target is the amount you can hold without harming your finances.
Is owning 0.1 BTC enough?
"Enough" is relative to your goal and cost of living, not an absolute. In scarcity terms, sub-1-BTC ownership is the norm rather than the exception. As with any amount, there is no guaranteed outcome.
How much bitcoin do I need to own a whole coin?
One full BTC - which most holders reach gradually rather than in a single purchase. Fractional accumulation, often via dollar-cost averaging, is the typical path. Note that lost coins keep shrinking the effective float over time.
Should I buy bitcoin all at once or over time?
Both are valid: lump-sum maximises time-in-market, while DCA reduces timing and behavioural risk. The trade-off is that DCA cushions the risk of buying just before a deep drawdown, at the cost of some upside in rising markets.
What percentage of my portfolio should be bitcoin?
There is no universal figure; the common institutional reference for a diversified portfolio is 1-2%. Above that, risk contribution scales non-linearly, so a small weight can dominate portfolio volatility. It remains personal - consider professional advice.
How much btc should I own to retire on it?
That depends on your retirement cost base and an unknowable future price, so no fixed number applies. This is not advice. A diversified, risk-sized approach is generally more durable than pinning retirement to one volatile asset.
Can I start investing in bitcoin with a small amount?
Yes. Bitcoin is divisible to eight decimal places, so entry does not require a whole coin - some structured products begin from $50. That divisibility is what makes gradual, small-step accumulation practical.
Does the amount of bitcoin I buy affect my taxes?
Tax treatment depends on your jurisdiction, and in many countries disposing of Bitcoin can trigger a taxable event regardless of amount. Rules differ widely by country and change over time. Consult a qualified tax professional for your specific situation.